

Opening a Bank Account in Spain: Online vs. Branch & Costs 2026

The rental agency in Málaga liked your application, and the flat with the little balcony is almost yours. Then the agent asks for a Spanish IBAN for rent and electricity. Suddenly your British or American account feels very far away. For most newcomers, opening a bank account in Spain is the first real piece of Spanish paperwork, often even before the Digital Nomad Visa appointment.
So which bank takes you before you hold a residency card, and what should it cost? We asked ourselves the same questions, and the rules are clearer than the queues at the branch suggest.
This guide shows you how resident and non-resident accounts differ, which documents banks really want and which accounts cost nothing to run. You also learn about the basic account Spanish law guarantees you, so you know your rights at the bank desk.
The Most Important Facts at a Glance
It sounds more complicated than it really is. Below you find out which account fits your situation and which papers to bring from home. We also walk you through the appointment, so the clerk doesn’t send you home empty-handed.
Why the account comes before the apartment
Landlords, utilities and internet providers all want a Spanish IBAN before you move in. That is why it is step one of seven in our free roadmap.
No spam, unsubscribe anytime. You’ll also get the key price and deadline updates for Andalusia straight to your inbox.
Opening a Bank Account in Spain: The Big Comparison
Spanish banks split their customers into two groups, residents and non-residents. Without a residency card (TIE), or while you still live abroad, you open a cuenta de no residente, a non-resident account. The quickest example we found is Santander’s Non-Resident Account. You open it online with your passport and a video call. It charges €0 in maintenance fees and asks for no salary or direct debits.
The catch sits in the small print, because Santander only accepts people living in 27 listed countries. The United Kingdom is on that list, the United States is not. Once you live here, more doors open. BBVA’s Cuenta Online Sin Comisiones also charges no maintenance fee, but it asks for a Spanish DNI or TIE. The table shows you the main options side by side, as we checked them on the banks’ own pages:
|
Account |
Who can open it |
What you need |
Maintenance fee (checked 07.10.2026) |
|---|---|---|---|
|
Santander Non-Resident Account |
Non-residents in 27 listed countries (United Kingdom yes, United States no) |
Passport, video call |
€0 |
|
BBVA Cuenta Online Sin Comisiones |
Residents |
DNI or TIE |
€0 |
|
CaixaBank HolaBank |
Non-residents |
Passport or ID, proof of income, branch visit within 6 months |
See the bank’s fee information document |
|
N26 Standard |
People living in Spain |
Photo ID, address in Spain |
€0 |
|
Basic payment account (cuenta de pago básica) |
Anyone living legally in the EU |
ID, anti-money-laundering checks |
At most €3 a month |
Why is my home country account not enough?
For a two-week holiday your British or American card is fine, but for living here it soon gets awkward. Landlords and electricity or internet companies want to set up a direct debit. Many of them expect a Spanish IBAN starting with ES. If you buy a home, the purchase money usually moves through a Spanish account. The yearly property tax (IBI) is easier to pay from one too. A local account also shows your landlord that you plan to stay.
- Buying property: The deposit and the payment at the notary run far more smoothly through a Spanish account.
- Running costs: You usually pay electricity, water and internet by direct debit from your account.
- Taxes & fees: Municipal taxes such as the IBI property tax can come straight off your local account.
- Proof of intent: Landlords see that you are settling in for good.
Option 1: The Fast Solution (Our Recommendation)
The online route suits you if you rent, work remotely or simply don’t need a Spanish mortgage. You skip the branch with its short morning opening hours and sort it out from your kitchen table instead.
Online banks with a Spanish IBAN give you an account number starting with ES. Your direct debits for electricity, water and internet then run as they would at any Spanish bank. N26 is one example, and its Standard account has no monthly maintenance fee. N26 asks for a photo ID and an address in Spain, so it fits once you have moved.
Are you still living abroad? Then Santander’s Non-Resident Account is the online option for people from the 27 countries on its list, including the United Kingdom. You enter your details, confirm your identity on a video call and accept the terms, and that is the whole process.
Your advantages with the online route:
- No maintenance fee: N26 Standard and Santander’s Non-Resident Account both charge €0 to run (checked 07.10.2026).
- No desk appointment: You open the account in the app or browser with a video identification.
- Spanish IBAN: You get an ES account number, so direct debits for luz, agua and internet work without arguments.
- Fewer papers: Santander’s non-resident account needs your passport, not a NIE, while N26 needs an address in Spain.
Expat Tip:
If you don’t need a Spanish mortgage, save yourself the headache of traditional banks. An online account with an ES IBAN covers rent and household bills for most people who live here.
Option 2: The Traditional Branch Bank (Caixa, BBVA, Sabadell)
The branch route suits you if you buy a home with a Spanish mortgage or regularly pay in cash. Big banks such as CaixaBank, Banco Santander or BBVA often link better mortgage terms to your main account. It pays to talk to them early.
CaixaBank’s HolaBank lets you start online as a non-resident with your passport or ID and proof of income. You then have to visit a branch within 6 months. Until you do, international transfers are restricted and cash deposits are capped at €600 a month.
What you need to know (The Downsides):
- Fees: Ask for the maintenance fee (comisión de mantenimiento) before you sign. You find the exact amount in the bank’s fee information document, and that is the paper to read, not the advert.
- Proof of non-residence: The bank wants to know that you still live abroad. Many ask for a certificate of non-residence, so ask at the start how often your bank wants it renewed.
- Branch dependency: For important signatures or account changes, you often have to show up in person at your own branch.
- FATCA (US citizens): With a US passport you fill in a FATCA self-certification. Spanish banks report accounts of US persons to the Spanish tax office every year (Modelo 290), which passes the data on to the US, so expect extra questions and call ahead.
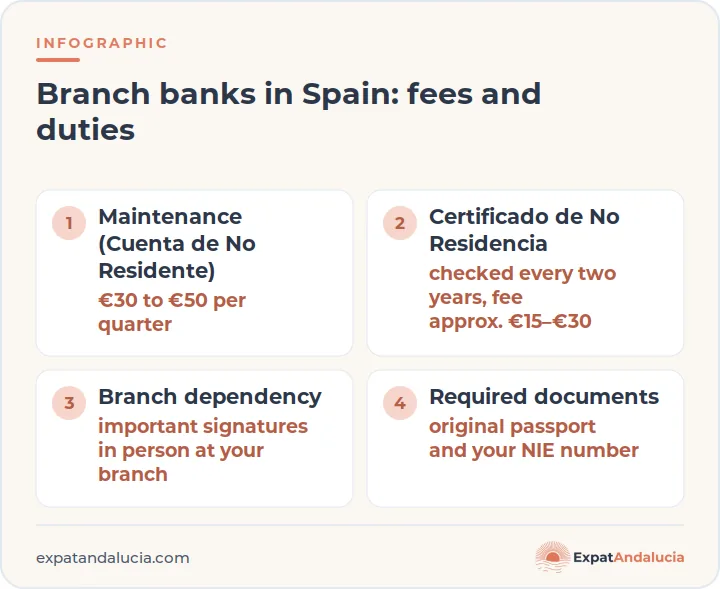
What non-residents need to know at CaixaBank, Santander or BBVA
The Documents You Absolutely Need
Every bank asks for slightly different papers, but with the following set you are on the safe side at the big banks. Bring the originals plus a set of photocopies. If a document is in neither English nor Spanish, the bank may ask you for a sworn translation (traducción jurada).
- Valid passport: The original, not a copy. A driving licence does not count as ID here.
- Your Spanish NIE number: The foreigner’s identity number on the white A4 sheet. Most banks ask for it, and you need it for taxes and contracts anyway. Santander’s Non-Resident Account opens with a passport alone, so a missing NIE doesn’t stop you there.
- Certificate of non-residence: You apply for the certificado de no residente with form EX-15, the same form as for the NIE, at a police office that handles foreigners’ paperwork. Ask your bank first whether it requests the certificate for you.
- Proof of income: Bring payslips, your latest P60 or W-2, a tax return or your employment contract. Spain’s anti-money-laundering law (Ley 10/2010) obliges banks to check your identity with reliable documents and to ask what you do for a living.
Your right to a basic payment account
If a bank turns you down, Spanish law gives you a fallback. A royal decree-law from 2017, the Real Decreto-ley 19/2017, gives everyone who lives legally in the EU the right to a basic payment account. In Spanish it is called cuenta de pago básica. People without a fixed address and asylum seekers are included, so you don’t need a Spanish passport or a long history with the bank.
The account covers what you need day to day. You pay money in, take it out and use a debit card. On top of that you get up to 120 transfers and direct debits a year within the EU. The Orden ECE/228/2019 caps the price for all of it at €3 a month. If your household income is low, you can even get the account free of charge (Real Decreto 164/2019).
The bank has to decide within ten working days of receiving your complete application. It may only refuse you for a few reasons. One is that you can’t provide the documents the anti-money-laundering rules require, another that you already hold a similar account in Spain. Ask for the cuenta de pago básica by name, so the clerk knows exactly which product you mean.
How you open your account at the branch, step by step
Walking into a Spanish bank branch can feel intimidating, but it doesn’t have to be. In the coastal areas with many expats, staff often speak some English. With the right papers and a little patience you get it done. Plan enough time, though, and don’t turn up just before closing.
- Pick your account: online, at a branch or as a basic payment account, depending on whether you live in Spain yet.
- Book an appointment (cita previa) online or by phone.
- Collect your passport, NIE, proof of non-residence or of your Spanish address and proof of income, plus copies.
- Sign the contract at the branch or in the app, and ask for the fee information document before you do.
- Activate online banking before you leave and wait for your debit card (tarjeta de débito).
From the Appointment to the Active Card
Walk-ins are often turned away, so book your cita previa first. At the appointment the clerk checks your documents and types everything into the system. Then you sign a small mountain of papers, on screen or on paper, which is completely normal. Ask about any clause you don’t understand. Once everything is signed, the account is usually active straight away.
Your debit card and PIN often arrive by post at your Spanish address, and some branches hand them over in person. Make sure you leave with your online banking login working, so you can handle everything from home. How paying by phone number works is covered in our guide to activating Bizum in Spain.
Our Expert Tip:
Our biggest mistake the first time around? We just marched into a branch without an appointment and were promptly sent packing. Our second mistake: We didn’t bring proof of income. The clerk looked at us like we were planning a heist. He only started the process once we produced a solid work contract. Learn from our errors: Book an appointment and bring ten documents rather than just two.
Your account is open, and the direct debits can start. The next cost waits at the transfer. Moving savings from pounds or dollars to a Spanish bank can eat money in exchange-rate markups and transfer fees. What that adds up to in practice is broken down in our guide to sending money to Spain.

Our recommendation: Wise account for euros and other currencies
With Wise you hold euros alongside pounds or dollars and send money at the real exchange rate, with the fee shown upfront. The euro account details are Belgian rather than Spanish, so keep your new ES account for Spanish direct debits and use Wise to fill it.
Affiliate link. It costs you nothing extra and we earn a commission.
Frequently Asked Questions

The account is only the start of the money side
Once you bank in Spain, the question of when you become a tax resident follows quickly. The Andalusia Masterplan explains the rules and the reporting duties that come with them.
Verdict
If you still live abroad, your passport alone can be enough. Santander’s Non-Resident Account costs €0 to run for people from its 27 listed countries. Once you live here, free online accounts and the basic payment account give you a Spanish IBAN as well, and the basic account costs at most €3 a month.
The costliest slip is signing at the branch without reading the fee information document. A maintenance fee you never asked about keeps running quietly every quarter, even though a free account was only one form away.
Still have questions?
Are you stuck with a specific bank, or has a requirement recently changed for UK/US citizens? Drop us a comment below!


